The Transport and Accessibility Explorer maps how travel options vary across Great Britain: public transport frequency back to 2004, vehicle ownership and electric vehicle uptake, and how easily residents can reach shops and services. For a full explanation of the tool please see the manual. You can also access sections of the manual via the help buttons ().
How can we improve this tool?
We would love to hear how you are using Carbon & Place and how we can make our tools more useful. If you have found an error in the data or a bug in the tool, you can also report it on GitHub.
Last updated: . If the page looks out of date, reload it while holding Shift (or press Ctrl+F5 on Windows, Cmd+Shift+R on a Mac) to bypass your browser cache.
We use cookies to measure how you use our website so we can understand how you interact with it, which helps us to make improvements. Find out more.
Basemap
Place names
Anti-alias
Layer Controls
Dasymetric
Click the population-weighted centroid of a neighbourhood to show 15-minute travel-time isochrones for different modes of travel.
Walking
Bicycle
Walk + Transit
Bike + Transit
Isochrones are calculated from weekday morning peak timetables, so off-peak and weekend reach will usually be smaller.
Bike + Transit assumes you can board the transit service with your bike and then use it
at the other end of your journey.
The PCT shows the roads where cycling could grow. The colours give the number of people who could be cycling along each road on a typical day, combining commuting and travel to school, under the scenario chosen above. See the PCT website or Lovelace et al. (2017) for how the estimates are made.
show names
show names
show names
show names
×
Help content loading…
×
Zone Summary: XXXXX
The 2022 Census in Scotland changed Data Zone boundaries substantially; historical data has been adjusted onto the new boundaries
This LSOA had a complex boundary change between 2011 and 2021; historical data is taken from the closest matching earlier LSOA
This LSOA was formed in 2021 by merging two LSOAs; their historical data has been added together
This LSOA was formed in 2021 by splitting an earlier LSOA; its historical data has been divided between the new areas
In at least one year, no residents were recorded in this LSOA
In some years this LSOA records an unusually large number of company cars
In some years this LSOA gives unreliable per-person figures because its recorded population is very low
Private vehicles by body type and licence
This chart shows the number of private vehicles in this area by body type and licence status. Licensed vehicles can be legally driven on public roads, while those with a Statutory Off Road Notification (SORN) are not registered for road use. Three types of vehicles are shown: cars, motorbikes, and other vehicles (mostly vans).
The size of the fleet matters as much as engine technology: parking demand, congestion, and embodied manufacturing emissions all scale with the size of the fleet. Councils can influence ownership through parking policy and controlled parking zones, support for car clubs, and ensuring new developments are genuinely usable without a car. Around a fifth of households have no car at all (National Travel Survey), so planning around universal car ownership underserves them.
Source: the DfT and DVLA vehicle licensing statistics, counted quarterly at the registered keeper's address, with the small counts that DfT suppresses for privacy infilled by a model, so treat any value below five as indicative. The same caveats apply to every vehicle chart: company vehicles sit at office addresses rather than where they are driven, SORN vehicles remain registered, and registration addresses lag house moves. See the manual.
Private vehicles fuel type and licence
This chart shows the number of private vehicles in this area by fuel type and licence status. It highlights the uptake of Battery Electric Vehicles (BEVs), which have zero exhaust emissions but still contribute emissions through electricity generation and manufacture. Ultra Low Emission Vehicles (ULEVs) are defined as vehicles producing less than 75g/km of CO2 at the exhaust. For some vehicles, notably plug-in hybrids, the official definition assumes usage patterns that may not reflect real-world use.
Accelerating EV uptake needs charging infrastructure matched to local housing: on-street and lamp-post charging where homes lack driveways, and rapid hubs on main roads. Uptake is strongly income-linked, so equitable policy also supports car clubs, e-bikes, and public transport rather than assuming universal electric car ownership. CREDS has published on the potential of both e-bikes and shared mobility.
Fuel categories follow DfT definitions; ULEV includes some efficient petrol/diesel and plug-in hybrids whose official ratings assume charging behaviour that may not reflect real-world use. Source: the DfT and DVLA vehicle licensing statistics, counted quarterly at the registered keeper's address, with the small counts that DfT suppresses for privacy infilled by a model, so treat any value below five as indicative. The same caveats apply to every vehicle chart: company vehicles sit at office addresses rather than where they are driven, SORN vehicles remain registered, and registration addresses lag house moves. See the manual.
Private vehicles ownership rate
This chart shows three measures of the ownership rate of private vehicles, per person, per adult, and per household. Each measure tells a different story about how vehicle ownership interacts with the demographics and needs of the population.
Ownership rates reveal car dependency, but the same number means different things in different places. High ownership where alternatives are good suggests habit and abundant parking, which pricing and street design can address; high ownership in rural areas reflects genuine need, where electric vehicle support and demand-responsive transport matter more. Falling per-household ownership among younger urban households (National Travel Survey) shows that change is possible where the alternatives exist.
Rates divide registered private vehicles by ONS mid-year population, adult population, and modelled household counts respectively; each denominator has its own uncertainty, so the trends matter more than exact values. Each line stops at the last year with a denominator, 2024 in England and Wales and 2022 in Scotland, even though the vehicle counts themselves run to 2025. Source: the DfT and DVLA vehicle licensing statistics, counted quarterly at the registered keeper's address, with the small counts that DfT suppresses for privacy infilled by a model, so treat any value below five as indicative. The same caveats apply to every vehicle chart: company vehicles sit at office addresses rather than where they are driven, SORN vehicles remain registered, and registration addresses lag house moves. See the manual.
Company vehicles by body type and licence
This chart shows the number of company vehicles in this area by body type and licence status. Company vehicles are those registered to a business or organisation rather than an individual.
Company fleets turn over quickly, typically every three to four years, and respond strongly to tax incentives, which makes them the fastest lever for electrifying the national fleet: today's company electric cars become tomorrow's second-hand electric cars. Benefit-in-kind rates that favour zero emission vehicles and salary sacrifice schemes have proven highly effective at shifting fleet purchases (company car tax rules).
Company registration at office addresses means these counts reflect where fleets are registered, not where vehicles operate; some neighbourhoods show implausibly large fleets for this reason. Source: the DfT and DVLA vehicle licensing statistics, counted quarterly at the registered keeper's address, with the small counts that DfT suppresses for privacy infilled by a model, so treat any value below five as indicative. The same caveats apply to every vehicle chart: company vehicles sit at office addresses rather than where they are driven, SORN vehicles remain registered, and registration addresses lag house moves. See the manual.
Company vehicles fuel type and licence
This chart shows the number of company vehicles in this area by fuel type and licence status.
Company fleet fuel mix leads the private market by several years thanks to benefit-in-kind incentives for zero-emission vehicles. Monitoring it locally shows the pipeline of EVs that will reach the second-hand market, and where workplace charging investment is needed.
Fuel categories follow DfT definitions, as for private vehicles. Source: the DfT and DVLA vehicle licensing statistics, counted quarterly at the registered keeper's address, with the small counts that DfT suppresses for privacy infilled by a model, so treat any value below five as indicative. The same caveats apply to every vehicle chart: company vehicles sit at office addresses rather than where they are driven, SORN vehicles remain registered, and registration addresses lag house moves. See the manual.
The accessibility and proximity analysis attempts to capture whether a neighbourhood is under- or over-provided with everyday services. One of the core principles of sustainable transport is that people's needs should be near where they live. Nearby services reduce travel distances and reduce energy consumption and emissions. They also make it more likely that people can use healthy and sustainable modes of travel like walking and cycling. Short travel distances also save people time and money.
Ideally, everything you need would be nearby, but that is not always practical. Especially as the number of services we need varies. For example, we have far more hairdressers than speech therapists because many people regularly go to the hairdressers, and very few people need a speech therapist. We therefore look at the ratio between the number of people and the number of services. For example, if there are 1,500 people within a 15-minute walk of your home, that could support around two hairdressers. But if only one hairdresser were within that distance, we would consider your neighbourhood underserved.
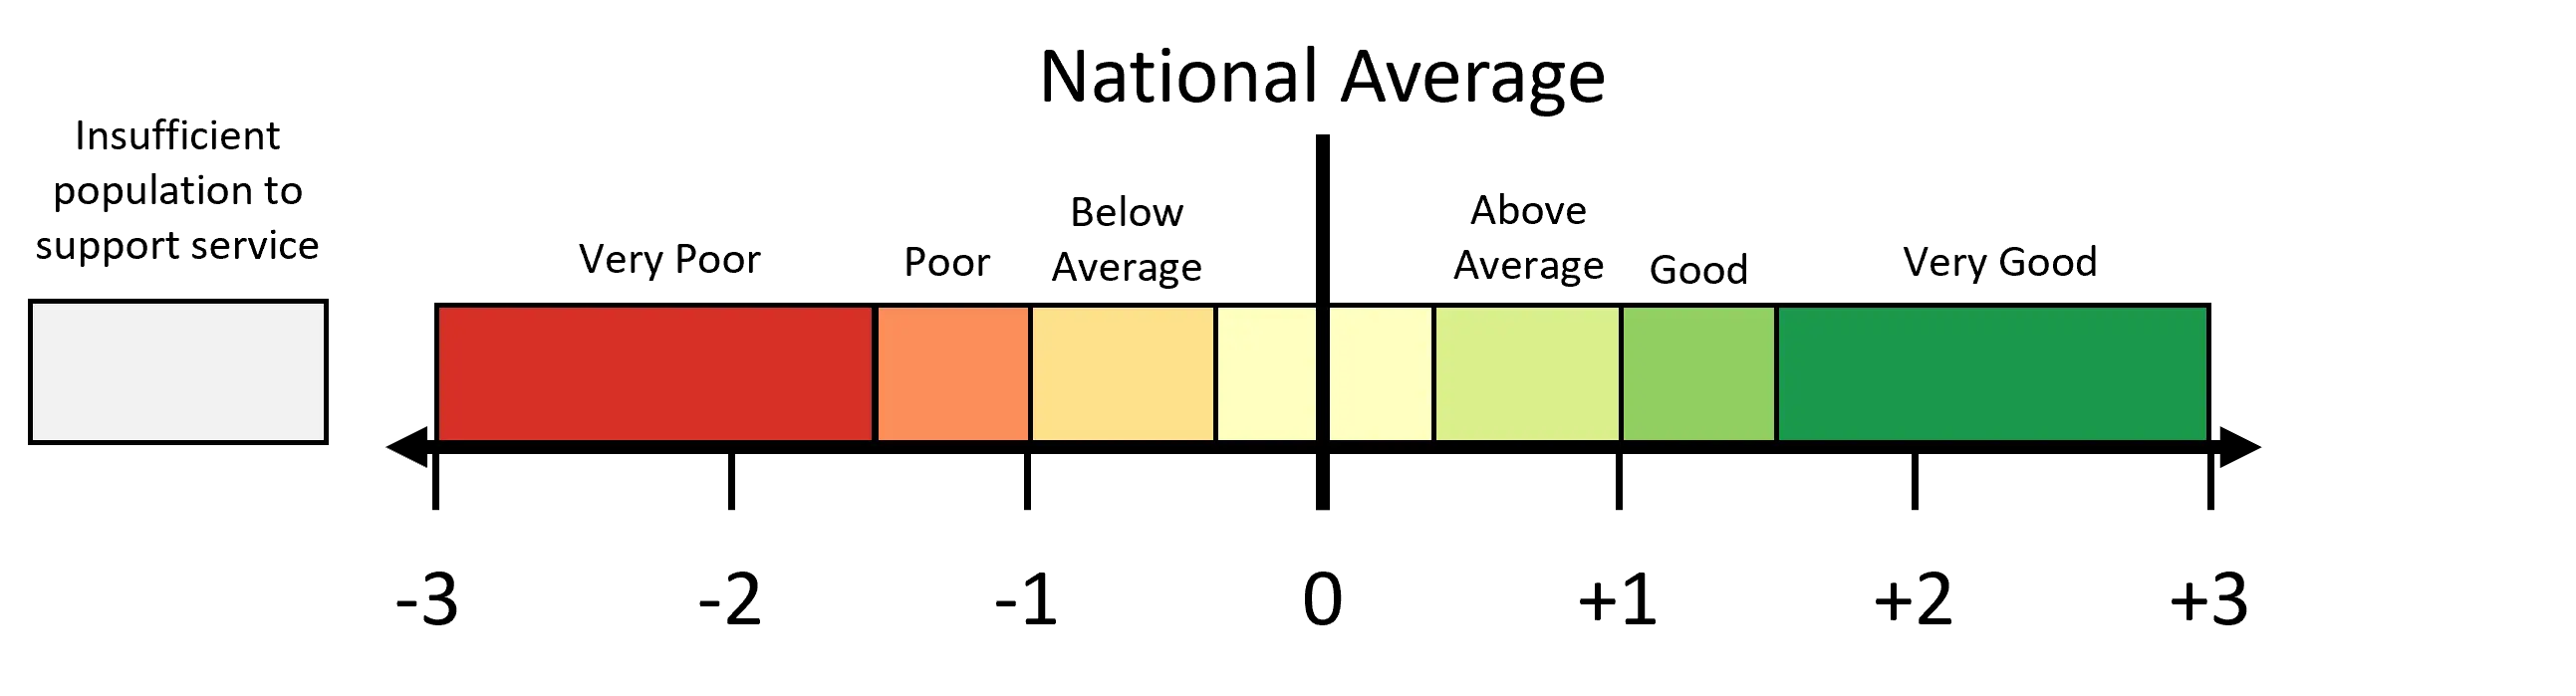
We can do this calculation for all kinds of services and produce a score between -3 and +3, where 0 means your neighbourhood has services in about the same proportion as the national average. A positive score means the area has more of that kind of service than average, and a negative score means it has fewer. The chart and table below summarise the scores for 385 types of service listed in the Ordnance Survey Points of Interest.
The scale shows how to interpret the Access and Proximity scores.
We look at different time and distance bands because some services are common (like hairdressers) while others are rare (like speech therapists). We measure travel time on foot and by public transport at 15, 30, 45, and 60 minutes (accessibility), and straight-line distance at 0.75, 1.5, 2.25, and 3 miles (proximity). For example, you may have no plasterers within 0.75 miles of your home, but plenty of plasterers within 1.5 miles of your home, and that is probably fine. But if your nearest postbox were 1.5 miles away, you would probably consider that too far.
The chart and table below present the same information in two formats, so that you can either scan the overall pattern or look up a particular kind of service. One caution before drawing conclusions: the scores are relative to the national distribution, so a service that is scarce everywhere in Britain still scores zero here.
This data is based off the 2022 ONS isochrones, which cover England and Wales only.
Accessibility & Proximity Summary Table
This chart shows one matched pair of columns from the table below; use the drop-down to change which. Each dot is a type of service (shops, schools, GPs, and so on): dots towards the top right are well provided both nearby and by public transport, while dots towards the bottom left are hard to reach, meaning longer, more car-dependent journeys for everyday needs.
Proximity is a planning outcome: local plans decide whether homes are built near services or far from them. Councils can use under-provision scores to target new services, protect existing local centres, require mixed-use development, and prioritise public transport where accessibility (not proximity) is the gap. This is the reasoning behind the "15-minute" and "20-minute neighbourhood" concepts now appearing in local plans and in TCPA guidance. The concept is contested, and critics argue it can be applied without regard to whether the services counted are ones people actually need or can afford; the summary table below lets you check which categories drive the score in this area.
Services come from the Ordnance Survey Points of Interest dataset (385 types, about 2.5 million destinations). For each neighbourhood we compute the population-to-service ratio within walking/public-transport travel-time bands (15/30/45/60 minutes, from timetable-based routing) and straight-line distance bands (0.75 to 3 miles), and express it as a score in standard deviations from the national average, truncated to the range -3 to +3. Limitations: POI data has classification errors and lags reality; travel times use timetables, not live services; scores are relative, so a service in short supply everywhere in Britain still scores 0 here; and Scotland is not covered. The manual sets out the method in full.
Accessibility & Proximity Summary Table
Public Transport Frequency
The chart shows the frequency of public transport (trips per hour) passing through or near this area, for each year from 2004 onwards, in five periods of the day: morning peak (6–10am), midday (10am–3pm), afternoon peak (3–6pm), evening (6–10pm), and night (10pm–6am). Frequency is what makes public transport usable without consulting a timetable, a "turn up and go" service. You can select the type of public transport and the day of the week from the drop-down menus. Note that 2012 and 2013 are missing due to a lack of data.
Bus service levels are a policy choice: since deregulation outside London, frequencies are set commercially unless authorities intervene. Franchising (as adopted in Greater Manchester), enhanced partnerships, bus priority lanes, and tendered evening and weekend services can all restore frequency. The long decline visible in many areas outside London reflects cuts to supported services documented in the official bus statistics; where frequency fell, ridership and access to jobs fell with it. Friends of the Earth used this dataset for their own analysis of Britain's bus decline.
Frequencies are computed from archived public transport timetables (2004 onwards), counting scheduled trips stopping in or near each neighbourhood per hour within each period. Limitations: the 2012 and 2013 timetable archives are unavailable; timetables record scheduled, not actual, services (cancellations and reliability are invisible); "near" uses a fixed catchment around each neighbourhood; and early years have patchier coverage for some operators. The whole archive was reprocessed in 2026, so these figures are not directly comparable with those published from earlier versions of the analysis. See the manual for details, and the PublicTransportAnalysis repository for the code.